Mortgage advice that starts with your deposit
Kestrel Lane Mortgages (sample) is an independent mortgage broker in Springfield. We compare deals from 40 lenders (sample) for first homes, moves, remortgages and buy-to-let, and handle the application with you.
A $360,000 home with a $36,000 deposit (sample)
Loan to value
0%60%75%80%85%90%95%100%
Loan $324,000, 90% of the price. Deposit $36,000, 10% of the price.
Loan $324,000 (90%) Deposit $36,000 (10%)
Lender bands: the largest loan as a share of the price, the deposit that band needs on this home, and the lenders on our panel lending in that band (sample).
Deposit from $144,000
40 of 40 lenders
Deposit from $90,000
40 of 40 lenders
Deposit from $72,000
38 of 40 lenders
Deposit from $54,000
34 of 40 lenders
Deposit from $36,000
29 of 40 lenders
Deposit from $18,000
17 of 40 lenders
Your home may be repossessed if you do not keep up repayments on your mortgage. Lenders make their own checks and decide whether to lend.
Mortgages we arrange
Each kind of mortgage has its own usual limit. The small tape shows the largest loan most lenders on our panel offer, as a share of the price or value.
First home
Buying for the first time with a deposit of 5% or more, saved, gifted or both.
Usually up to 95% of the price as a loan. Usually up to 95% of the price
Moving home
Selling one home and buying the next: keeping your current deal, or a new one for the new home.
Usually up to 95% of the price as a loan. Usually up to 95% of the price
Remortgage
Your deal is ending, or you want to borrow more for building work. We compare it with staying where you are.
Usually up to 90% of the price as a loan. Usually up to 90% of the value
Buy-to-let
A home to let, in your name or a company’s. Lenders look at the rent as well as your income.
Usually up to 75% of the price as a loan. Usually up to 75% of the price
Self-employed
Sole traders, partners, contractors and company directors with one or two years of accounts.
Usually up to 90% of the price as a loan. Usually up to 90% of the price
Usual limits across our panel (sample); each lender sets its own.
From first call to completion
Six steps. We do the paperwork and the chasing; you sign at the end. Typical times (sample) are on the right.
A free first call
Twenty minutes about the home, your income and your deposit. We say what we charge before going further.
Same week
Fact-find and documents
We go through your income, spending and credit history with you, and collect payslips, statements and ID.
About a week
Agreement in principle
A lender’s first look at your case, so estate agents know you are ready. It is not a mortgage offer.
One to two days
Application and valuation
We send the full application and the lender values the home. We chase it until the lender decides.
Two to four weeks
Mortgage offer
The lender’s written offer. We go through every condition with you before your solicitor takes over.
When the lender decides
Completion
Your solicitor draws down the loan and the home is yours. We note when your deal ends.
Set by the sale
What to have ready
Lenders ask for the same papers in almost every case. Having them ready saves a week or more.

Everyone
- Photo ID: passport or driving licence
- Proof of address from the last three months
- Your last three payslips
- Three months of bank statements
- Where the deposit comes from: savings statements or a gift letter
If you are self-employed
- Two years of accounts or tax calculations
- Tax year overviews for the same years
- Six months of business bank statements
- Company directors: salary and dividends paid
How we are paid
The first call costs nothing. If you go ahead, there is one advice fee, and the lender usually pays us a fee too. You see both before you apply.
First call and comparison
Free
Advice fee, paid when you apply
Not charged if the lender declines your application
$495
Remortgage for an existing client
$295
Buy-to-let and limited company cases
$695
Commission from the lender
Lenders pay brokers a fee on completion; the amount is in your mortgage illustration
Shown in your documents
Example prices.
What the fee covers
- A search of all 40 lenders on our panel (sample)
- Your fact-find, documents and the application
- Chasing the lender, the valuer and the solicitors
- Going through the offer with you, line by line
- A reminder six months before your deal ends
When your deal ends, we write first
Most mortgage deals run for two to five years. Six months before yours ends, we compare staying with your lender against moving, so you never drift onto the lender’s standard rate without knowing.
- A reminder letter six months before the end date
- A comparison with your current lender's own offer
- No fee if staying where you are is the better choice

Your advisers
Three advisers and a case manager. You keep the same adviser from the first call to the keys (sample).
Ruth Calloway
Mortgage adviser and founder (sample)
First homes and moving home; started the firm in 2011.
Samir Haddad
Mortgage adviser (sample)
Self-employed and company directors, buy-to-let and limited companies.
Jo Whitfield
Mortgage adviser (sample)
Remortgages, borrowing for building work and later-life lending.
Ellen Park
Case manager (sample)
Chases lenders, valuers and solicitors and keeps you posted each week.
Guides
-
Loan to value: the one number every lender starts with
- Details
- October 11, 2026
How the split between deposit and loan decides which lenders you can choose from (sample guide).
-
Remortgaging: when to start looking
- Details
- October 6, 2026
Why six months before your deal ends is the right time to compare (sample guide).
-
The documents a lender will ask for
- Details
- October 1, 2026
A checklist for employed and self-employed borrowers (sample guide).
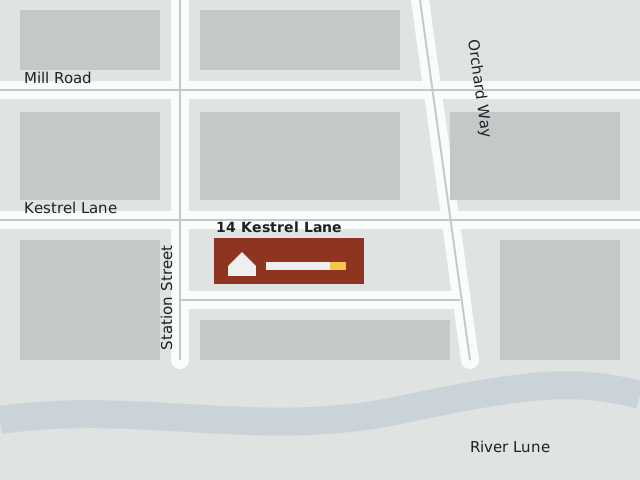
Visit the office
14 Kestrel Lane, first floor
Springfield (sample)
Monday to Friday
08:30–18:00
Saturday
09:00–13:00
Evening calls
By appointment
Opening times (sample). Most first calls happen by phone or video; the office is up one flight of stairs, and we meet at the ground-floor café when that suits better.